Georgia homeowners insurance: how roof age affects your rates
Georgia homeowners insurance: how roof age affects your rates
If you've gotten a homeowners insurance quote lately and wondered why the price jumped, your roof might be the reason. In Cartersville and across Georgia, roof age is one of the single biggest things insurance companies consider when they calculate your rate. I see this come up constantly in my office, and it surprises people more often than not.
Here's the honest truth: insurers aren't being picky just to be difficult. An older roof has a higher chance of leaking, and water damage claims are expensive. So when your roof hits a certain age, carriers either charge more, require an inspection, or sometimes they just decline to insure you at all. Let me walk you through how this actually works and what your options are.
Why insurers care so much about roof age
Most roofing materials have a predictable lifespan. Asphalt shingles, which are everywhere in Bartow County, typically last 20 to 25 years if they're installed and maintained well. Wood shakes might go 30 years. Metal roofs can last 40 to 50 years or longer. Insurance companies have decades of claims data that tells them exactly when roofs fail and how much water damage costs to repair.
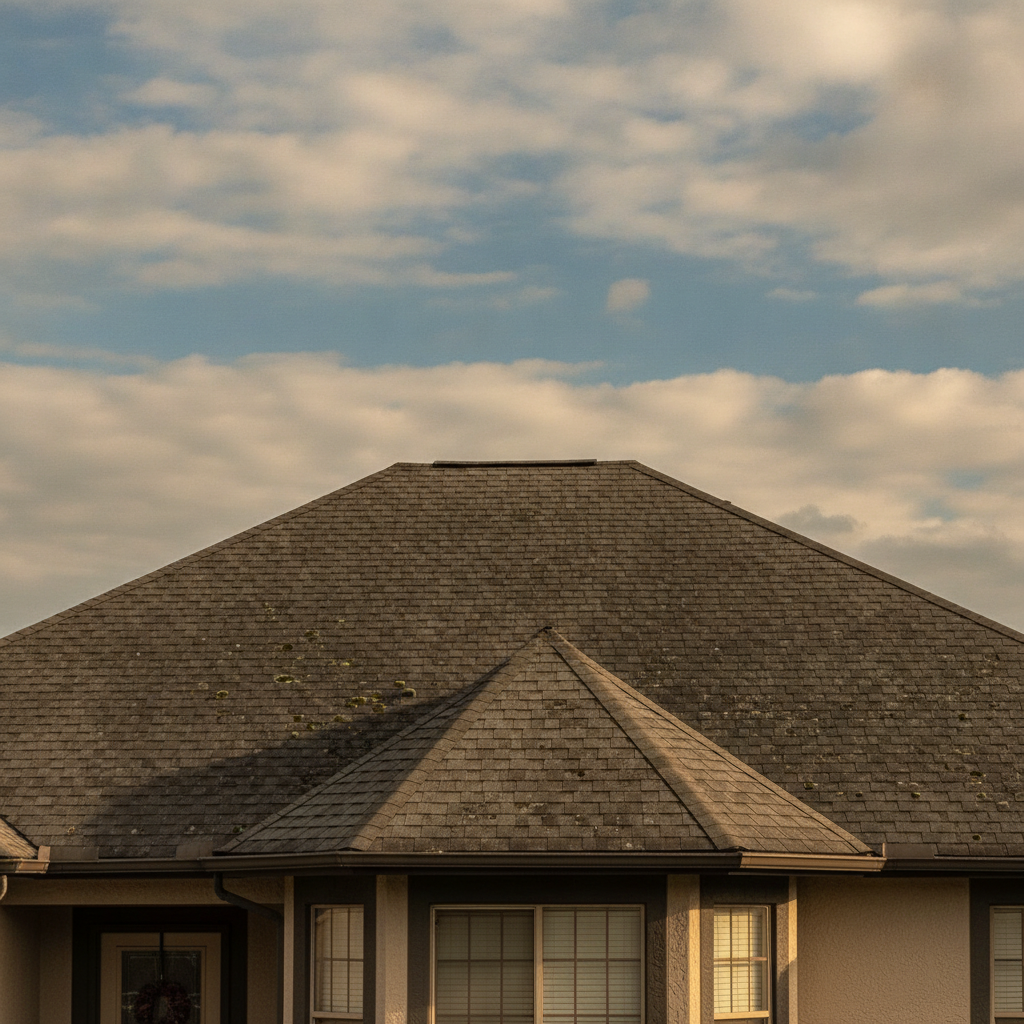
The risk changes dramatically around year 18 to 20 for a shingle roof. Before that point, claims are rare. After that point, they climb. A roof that's 22 years old has a measurably higher chance of a claim than one that's 15 years old. That's not opinion, that's math based on what actually happens in the real world.
So when you apply for a policy or renew one, the carrier checks your roof's age. If it's over a certain threshold, they'll either raise your premium, send an inspector out to look at it, or both. Some carriers won't touch it at all.
What actually happens to your rates as your roof ages
I'll be straight with you: the jump isn't always gradual. Most carriers have tiers. Your roof at 18 years might not trigger anything. At 20 or 21 years, suddenly you're in a higher risk category and your rate goes up. Sometimes it's 10 percent. Sometimes it's more. At 25 to 30 years, many carriers won't insure you, period, or they'll charge a premium that makes it not worth it.
The tricky part is that different carriers have different rules. One company might be fine with a 25-year-old roof if it's been well maintained. Another will decline it at 22. That's exactly why The East Agency shops 20+ carriers to find the best rate for each person. We know which carriers are flexible on age and which ones are strict, and we use that to save our customers real money.
Even a small difference in how a carrier views roof age can mean hundreds of dollars a year in your favor.
What you can do if your roof is getting older
If your roof is between 15 and 25 years old, you have time to plan. Get it inspected by a professional roofer, not just your insurance company's inspector. Find out what kind of shape it's actually in. Sometimes a roof that looks fine from the ground holds up well past its normal lifespan. Sometimes one that's only 18 years old is already failing. Condition matters.
If you know your roof needs to be replaced soon, consider doing it before you shop for insurance or renew your policy. A new roof can cut your rate significantly, and you'll also reduce the actual risk of a costly water damage claim down the road. That's a win for your wallet and your home.
If you're not ready to replace it yet, make sure whoever is insuring you knows about any maintenance you've done. New flashing, new gutters, or a fresh coat of sealant can matter to some carriers.
Getting the right coverage at the right price
The biggest mistake I see is people thinking all insurance companies are the same. They're not. When it comes to roof age and rates, there's actually a lot of room to shop and compare. You might get declined somewhere and quoted at a fair price somewhere else, just because of how different carriers view risk.
That's why it pays to work with someone who actually knows the carriers. We've been doing this long enough in Cartersville to know which companies will work with you on an older roof and which ones are going to be strict about it. We also know how to present your situation to get you the best offer.
If you want to know where your roof stands and what it might cost to insure your home, reach out and let's talk through it.
Questions or ready to see your actual options? Let's figure out what makes sense for your situation: https://brannoneast.agency/home-insurance-quote.html or just call or text me at (678) 562-6905. I'm here to help.